Utility Easements, Rights-of-Way, and Hidden Encumbrances at Tax Deed Auctions: What Every Investor Must Know Before Bidding
You win a tax deed auction, record your deed, and start planning a renovation—then a utility crew shows up and says they own the right to dig through your front yard whenever they want. Easements, rights-of-way, and other encumbrances run with the land, not with the owner, and they survive even the cleanest tax deed sale. Understanding what kinds of encumbrances exist, how to find them, and what they mean for value and usability is one of the most overlooked layers of due diligence in distressed-property investing.
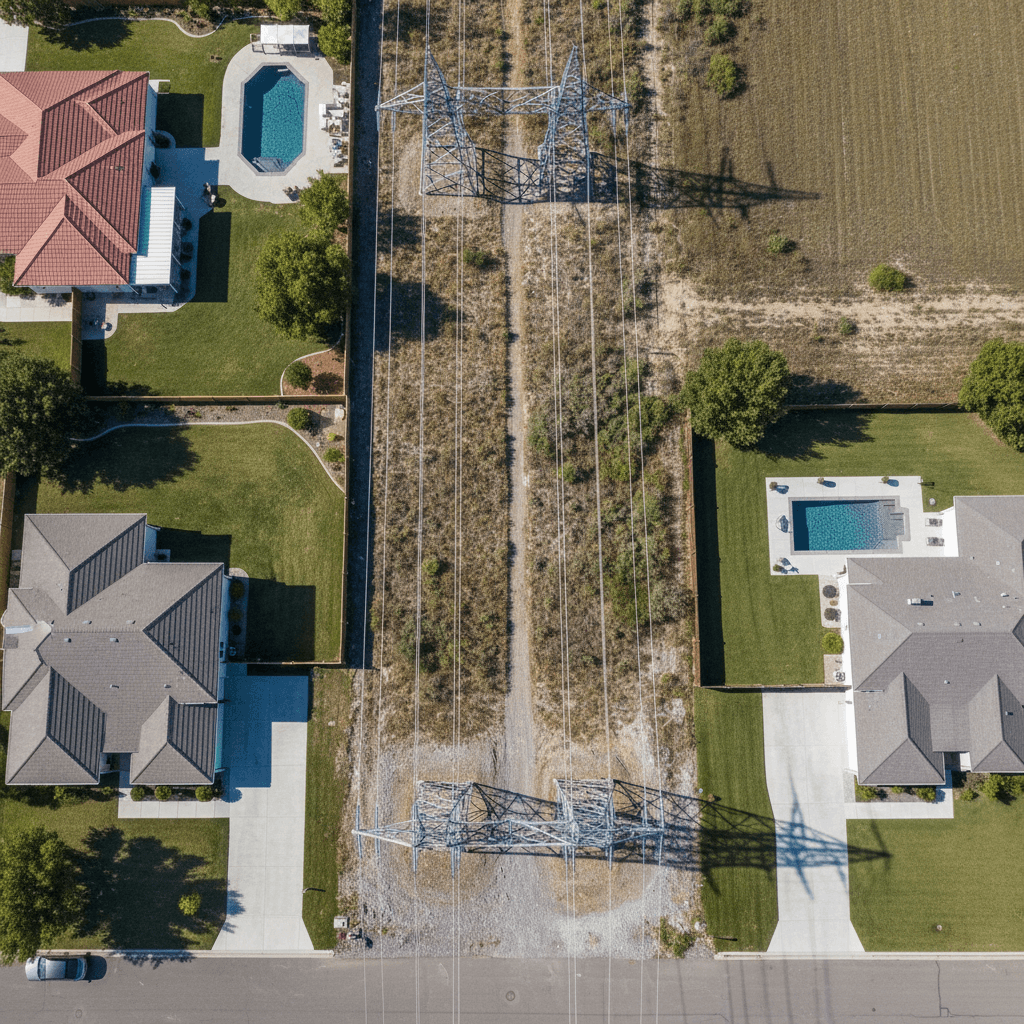
What Is an Easement and Why Does It Survive a Tax Deed Sale?
An easement is a legal right held by a person or entity—other than the owner—to use a specific portion of a parcel for a defined purpose. Common holders include electric utilities, natural gas companies, telephone and cable providers, municipal water and sewer departments, neighboring landowners, and government road agencies. Unlike a mortgage or a judgment lien, an easement is not a debt instrument—it is a use right attached to the land itself. Because property tax foreclosure extinguishes ownership interests in the delinquent taxpayer, but does not extinguish third-party use rights that were properly recorded before the tax lien arose, easements almost universally survive the deed transfer.
This means every investor who purchases at a tax deed auction acquires the property subject to any and all recorded easements—and potentially some unrecorded ones depending on state law. The county is not going to remind you about this at the auction podium. The responsibility to discover encumbrances before you bid is entirely yours.
- Utility easements (electric, gas, water, sewer, telecommunications)
- Drainage and stormwater easements
- Road and access easements
- Railroad rights-of-way
- Conservation and open-space easements
- Pipeline easements
- Driveway and shared-access easements for neighboring parcels
How Easements and Rights-of-Way Can Destroy a Development Plan
The practical impact of an easement depends entirely on its location, width, and terms. A narrow utility easement running along the back fence line of a residential lot may be a minor inconvenience. A fifty-foot-wide electric transmission right-of-way cutting diagonally across a parcel can render the affected area unbuildable, slash insurance costs, depress value, and make conventional financing nearly impossible. Pipeline easements—particularly those carrying natural gas, petroleum products, or hazardous materials—carry not only buildability restrictions but also regulatory requirements about excavation, grading, and structures near the corridor.
Railroad rights-of-way present a particularly complex problem. Historical rail corridors are sometimes subject to federal surface transportation law that can override state property rights in ways that are not fully resolved even decades after a rail line is abandoned. A parcel that appears fee-simple on a county plat may actually be encumbered by a reversionary interest or a federal rails-to-trails conversion that limits your ownership rights in ways no county recorder will flag for you.
Conservation easements deserve special attention in rural and semi-rural markets. A prior owner may have voluntarily granted a conservation organization the right to restrict development in perpetuity in exchange for a tax benefit. That restriction follows the deed. If you buy the parcel at a tax deed auction, you own it subject to the conservation easement regardless of whether you were aware of it.
- Wide transmission corridors may prevent any permanent structure in the affected strip
- Pipeline easements often prohibit grading, deep excavation, or tree planting above the line
- Conservation easements can permanently cap density regardless of zoning
- Railroad corridors may carry federal rights that complicate your title for years
Recorded vs. Unrecorded Encumbrances: The Research Gap That Costs Investors Money
A properly recorded easement should appear in the grantor-grantee index or the parcel's chain of title at the county recorder's office. However, recorded does not always mean easy to find. Easements granted decades ago may be buried in deeds several ownership generations back. Utility companies sometimes recorded blanket easements covering large areas rather than individual parcels, meaning the encumbrance may not attach to your specific parcel number directly—you may need to trace the legal description in the blanket grant to determine whether your property falls inside it.
Unrecorded easements are a separate problem. Many states recognize prescriptive easements—use rights that arise from long, open, continuous, and adverse use of land without formal permission—that are never recorded anywhere. If a neighbor has been using a footpath across a corner of your parcel for twenty years, they may have acquired a legally enforceable easement by prescription even though nothing appears in the recorder's records. Implied easements based on prior common ownership can also exist without a recorded document. A title attorney can give you a legal opinion on what risks exist, but even they cannot guarantee that every unrecorded claim has been identified.
This is why investors who rely solely on the county's online parcel viewer or a basic tax-record search are operating with incomplete information. A full title search through the chain of title, combined with a physical inspection of the property for signs of use by third parties, is the minimum responsible approach before committing capital at auction.
- Search the grantor-grantee index, not just the parcel number
- Look for blanket utility grants covering blocks, plats, or sections
- Walk the property and note utility poles, markers, pipeline warning signs, worn footpaths, and shared driveways
- Ask a title professional whether prescriptive or implied easements are likely given the property's history
Rights-of-Way: Government Claims That Are Easy to Miss
A right-of-way (ROW) is a specific type of easement granting the right to travel over land, and government road agencies hold enormous quantities of unrecorded or informally documented ROWs across the United States. A county road that has existed for a century may have no formally recorded right-of-way agreement—the road simply exists, the county maintains it, and everyone assumes the adjacent property owner's land extends only to the road edge. When you buy the parcel at a tax deed auction and commission a survey, you may discover the actual record boundary of your lot extends into what is currently a paved road—and the county will assert its ROW rights regardless.
State Departments of Transportation hold ROWs along highways that may extend significantly further than the current pavement edge, preserving future expansion corridors. Federal highway programs can add additional layers. In some rural states, section-line roads—theoretical road corridors established on government land survey lines—give the public a right of travel even where no road has ever been physically built, and those rights can encumber private parcels.
Electric utility and telecommunications ROWs on rural properties are sometimes recorded only with the utility company's internal records or with a federal agency rather than the county recorder. Due diligence should include contacting major utility providers serving the area and requesting easement maps for the specific parcel, in addition to the standard title search.
- Verify road ROW width with the county road department before assuming a buildable setback
- Check with state DOT for highway expansion corridors
- Contact local electric, gas, and telecom providers for their internal easement records
- In rural areas, research whether section-line road rights exist under state law
How to Evaluate Easement Risk Before You Bid
The evaluation process starts with the property description, not the auction listing. Pull the legal description from the county recorder, then run the chain of title back far enough to identify any conveyances that carved out or reserved use rights. In states with a Torrens title system, check the certificate of title for noted encumbrances. Review any existing survey or plat map filed with the recorder—a survey will typically show recorded easements graphically and is often more useful than trying to interpret a metes-and-bounds description in a text document.
On the ground, look for physical indicators: utility poles and guy wires, buried-line markers with pipeline company names, concrete survey monuments at unusual offsets, evidence of regular mowing or maintenance by someone other than the current occupant, and shared driveways or paths worn into the soil. These observations may point to easements that do not appear cleanly in the records.
After gathering what you can independently, bring in a licensed surveyor and a real estate attorney familiar with the county before committing to a large bid. The cost of a professional opinion is modest compared to the risk of acquiring a parcel where a utility company has the right to run heavy equipment across the buildable area every time a line needs maintenance. Price the easement burden into your maximum bid—it is a real reduction in the property's utility and value, not an abstraction.
Tools that aggregate risk signals across multiple categories—title flags, recorded liens, environmental markers, and encumbrance indicators—can help investors triage which parcels warrant deeper investigation before spending money on professional due diligence. The goal is to identify serious problems early, before auction day, when you still have the option to walk away.
- Pull the full chain of title, not just the most recent deed
- Obtain or order a current survey if one is not already recorded
- Walk the property and document physical evidence of third-party use
- Get a professional opinion for any parcel where the easement picture is unclear
- Adjust your maximum bid to reflect permanently reduced buildability or utility
Score every auction before you bid
TaxDeedIQ gives every US tax deed & tax lien auction a 0–100 safety score, surviving liens, IRS redemption, flood, homestead.
Start my free trialUtility Easements, Rights-of-Way, and Hidden Encumbrances at Tax Deed Auctions FAQ
Do easements automatically go away when a tax deed is issued?
No. Easements are use rights attached to the land, not ownership interests of the delinquent taxpayer. Because property tax foreclosure wipes out the prior owner's equity and certain subordinate liens, but does not extinguish third-party rights in the property that predate or are senior to the tax lien, recorded easements survive the sale and bind whoever takes title through the tax deed.
What is the difference between an easement and a lien when it comes to tax deed auctions?
A lien is a financial encumbrance—a claim against the property to secure payment of a debt, like a mortgage or a judgment. Liens may or may not survive a tax deed depending on their priority and the state's statute. An easement is a use right, not a debt, and is not extinguished by the tax foreclosure process. Think of a lien as a financial cloud on title and an easement as a permanent restriction on what you can do with the land itself.
How do I find out if a property has utility easements before I bid at auction?
Start with a full chain-of-title search at the county recorder using the legal description, not just the parcel number. Review any filed plat maps or surveys for the property. Contact the major utility providers—electric, gas, telecommunications, water, and sewer—serving the area and ask whether they have recorded or unrecorded easements on the parcel. Walk the property and look for physical indicators like buried-line markers, utility poles, or signs of regular maintenance by third parties. For high-value bids, hire a licensed surveyor and a title attorney to review the findings and give you a professional opinion before auction day.
Can a conservation easement be removed after I buy a tax deed property?
Conservation easements are typically granted in perpetuity to qualified conservation organizations and are designed to survive ownership changes, including tax deed transfers. Removing or modifying one generally requires the consent of the easement holder and, in many cases, involves a complex legal process. Investors should treat a conservation easement as a permanent restriction on the parcel and price their bid accordingly rather than assuming it can be negotiated away after purchase.
Does the auction listing have to disclose easements?
In most jurisdictions, tax deed auction listings provide minimal disclosure. The county's legal obligation is generally to notify the delinquent taxpayer and lienholders as required by statute, not to provide investors with a comprehensive encumbrance report. Relying on auction marketing materials or the county parcel viewer as a substitute for actual title research is one of the most common and costly mistakes investors make in this space. Evaluate the risk before you bid—not after the gavel falls.
More guides
- Tax Deed vs Tax Lien: What's the Difference? (2026 Guide)
- Is Tax Deed Investing Safe? 6 Risks to Check Before You Bid
- Tax Deed Surplus Funds: How Overbid Recovery Works
- Redeemable Deed States Explained (Georgia, Texas & More)
- Probate Estates, Heir Disputes, and Ownership Gaps at Tax Deed Auctions: What Every Investor Must Evaluate Before Bidding
- Special Assessments and Municipal Improvement Districts at Tax Deed Auctions: What Every Investor Must Know Before Bidding
Informational only, not legal or investment advice. Confirm rules with the county and consult a licensed professional before bidding.