Special Assessments and Municipal Improvement Districts at Tax Deed Auctions: What Every Investor Must Know Before Bidding
Special assessments are one of the most overlooked cost layers at tax deed auctions. Unlike general property taxes, these charges are levied for specific public improvements — streets, sewers, drainage, lighting — and in many states they survive the tax deed sale entirely, landing on the new owner's ledger the moment the gavel falls. Before you bid on any parcel, you need to understand exactly what improvement-district obligations are attached to it and whether your winning price still leaves any margin after you pay them off.
What Special Assessments Are and Why They Exist
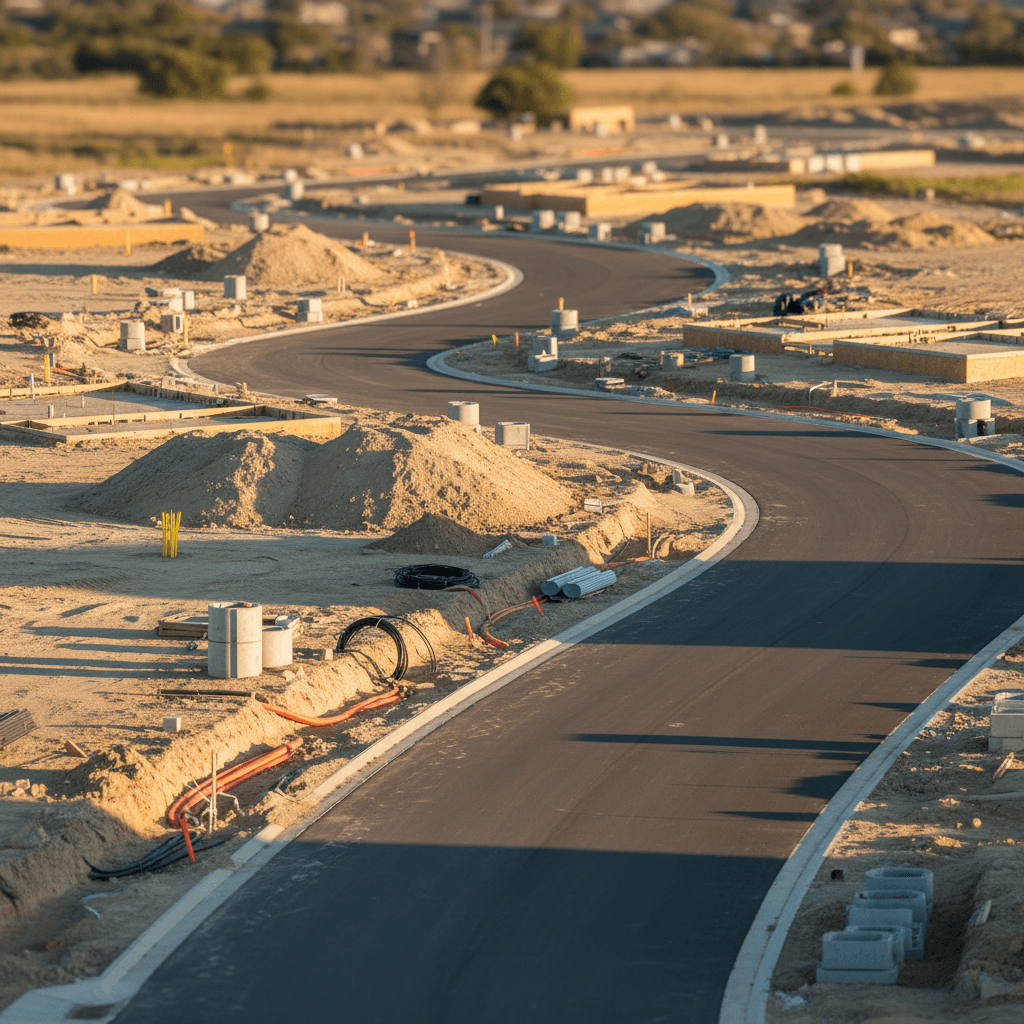
A special assessment is a government-imposed charge levied against a specific parcel because that parcel is deemed to benefit from a defined public improvement. A subdivision that gets a new water main, a downtown block that joins a business-improvement district, a coastal community that funds a seawall — all of these create assessments that attach to individual properties rather than being spread across the general tax base. Unlike property taxes, which fund broad government operations, special assessments are project-specific and legally tied to the land itself.
Because the charge follows the land and not the owner, the central question for any tax deed investor is straightforward: does the jurisdiction's foreclosure statute extinguish these assessments the same way it extinguishes mortgage liens and judgment liens? The honest answer is: sometimes, but far from always. The outcome depends on the type of district, the state statute, and — critically — how the assessment was created and recorded.
- Street and sidewalk improvement assessments
- Water, sewer, and stormwater district levies
- Community Development District (CDD) bonds and annual assessments
- Business Improvement District (BID) annual charges
- Special Lighting or Landscaping District fees
- Levee and flood-control district assessments
Do Special Assessments Survive a Tax Deed Sale?
The survival question is not uniform across states, and investors who assume that any one answer applies everywhere routinely get burned. In several states, the tax deed process is designed to produce a "clean" title, meaning most liens — including special assessments — are wiped out upon issuance of the deed. In other states, special assessments run with the land and are explicitly excluded from the lien-extinguishment effect of the tax deed.
Florida is a well-known example of nuance: annual CDD assessments are generally treated as a recurring obligation that the new owner must continue paying, while the bonded portion of a CDD debt — the capital improvement bond backed by assessments — has generated significant litigation over whether it survives a tax certificate foreclosure. Even within a single state, courts have sometimes drawn different conclusions depending on whether the bond was issued before or after the delinquent tax year, or whether the district followed proper recording procedures. The bottom line is that you cannot assume survival or extinguishment — you must research each district's enabling legislation and recorded instruments.
In states where assessments survive, the buyer steps into the prior owner's shoes. That can mean assuming not just the current year's installment but any delinquent installments that have accumulated, plus interest and penalties. In bonded improvement districts, the remaining bond principal allocable to a single parcel can easily reach into the tens of thousands of dollars.
Community Development Districts and Mello-Roos: The High-Dollar Examples
Two special-assessment structures deserve particular attention because of the dollar amounts involved. Community Development Districts, most prevalent in Florida but found in other states, are independent special-purpose governments authorized to issue bonds to finance infrastructure in new developments. A single residential parcel in a CDD may carry an annual debt-service assessment that persists for decades until the underlying bond matures. If the annual CDD assessment is not extinguished by the tax deed, the investor owes it going forward — and if prior-year assessments accumulated during the foreclosure process, those arrears may also pass to the buyer depending on state law and the district's own covenants.
California's Mello-Roos Community Facilities District levies operate under a similar framework. Parcels in a Mello-Roos district carry a special tax that funds bonds issued for infrastructure improvements. These levies are recorded on the county tax roll alongside property taxes, which creates its own complication: some Mello-Roos delinquencies trigger their own separate foreclosure timeline that is entirely independent of the property tax foreclosure proceeding. An investor purchasing at a tax deed sale in California may find that the Mello-Roos lien survived because it had not been included in the foreclosing tax bill or because the district pursued its own enforcement action.
The takeaway is not that CDDs or Mello-Roos districts make a property uninvestable — many properties in these districts are perfectly viable acquisitions — but that the annual carrying cost and any delinquent arrears must be factored into your maximum bid before the auction, not discovered afterward.
- Review the property tax bill for line items beyond ad valorem taxes
- Order a CDD or special district estoppel letter before bidding if permitted
- Search for separate Mello-Roos district foreclosure filings on the parcel
- Request the district's bond maturity schedule and per-parcel annual assessment
- Determine whether delinquent installments survive or are wiped by the deed
How to Find Special Assessment Obligations Before the Auction
Research starts with the property tax bill. Most counties display not just the ad valorem tax but each special-assessment line item on the same bill. A parcel in a lighting district, a water-management district, and a CDD will show three separate line items in addition to county and school taxes. Reviewing a recent tax bill — which you can usually pull from the county property appraiser or treasurer website — tells you the annual ongoing cost immediately.
Beyond the tax bill, check the county recorder's index for recorded notices of special assessments or improvement liens. Many districts are required by statute to record a notice of lien against each parcel in their district. These instruments will name the district, describe the improvement, and sometimes state the original principal amount. If the parcel is in a platted subdivision, the plat itself may reference a community facilities district or a private roads-and-utilities district with assessment authority.
Call the relevant district or municipality directly. Most special districts have a finance officer or bond trustee who can tell you the current balance of outstanding assessments, the annual payment schedule, and whether any arrears exist. This call takes minutes and can prevent a costly mistake. Some districts also publish per-parcel assessment tables on their own websites. Verify the information with the county, and if significant dollars are at stake, engage a title company or real estate attorney familiar with local special-district law before finalizing your bid.
Pricing the Risk Into Your Bid
Once you have identified that a parcel carries a surviving special assessment, the financial math must adjust accordingly. If an improvement-district obligation runs with the land and you will owe it as the new owner, that obligation is functionally equivalent to any other carrying cost. If the assessment also carries delinquent arrears that pass through the sale, the total amount you must cure before you can convey clean title becomes part of your effective acquisition cost.
Build your maximum bid by working backward from the property's after-repair value or rental income potential. Subtract repair costs, holding costs, transaction costs, and — critically — the full amount of any surviving special assessments you will need to pay down or continue servicing. Only after all of those deductions should you arrive at your ceiling bid. Overpaying because you did not account for a CDD bond or a downtown BID annual charge is among the most avoidable mistakes in tax deed investing, because the information is almost always publicly available before the auction.
Tools that aggregate public-record data on a parcel can accelerate this process materially. Knowing what the assessment obligations are, whether they survived the foreclosure, and how they fit into the property's total cost structure is exactly the kind of risk-layer analysis that separates disciplined bidders from those who win auctions and lose money. Verify your findings with the county and, where the amounts are material, with a licensed professional who understands the specific district's governing documents.
It's the 3% that bankrupts beginners
95% of tax liens get paid. TaxDeedIQ finds the risky ones, the junk land, the surviving IRS lien, before you bid.
Try it free for 7 daysSpecial Assessments and Municipal Improvement Districts at Tax Deed Auctions FAQ
Do special assessments always survive a tax deed sale?
No. Whether a special assessment survives depends on the state statute governing the tax deed foreclosure, the type of district that imposed the assessment, and how the assessment was recorded. In some states the tax deed wipes out most liens including special assessments; in others, improvement-district charges expressly run with the land and are not extinguished. You must research the specific parcel, district, and state law before bidding — never assume one way or the other.
How do I find out if a property is in a special assessment district before bidding?
Start with the property's most recent tax bill, which typically lists all special-assessment line items alongside the ad valorem tax. Then search the county recorder's index for recorded district notices on the parcel. Review the subdivision plat for references to community facilities or improvement districts. Finally, contact the district's finance office or bond trustee directly to request the current balance, annual payment, and any delinquent arrears. Confirm everything with the county and, for large amounts, consult a local real estate attorney.
Can a CDD bond obligation make a tax deed investment unprofitable?
Yes, if the bond's per-parcel assessment is large, the bond maturity is distant, and the obligation survives the tax deed, the annual carrying cost can erode or eliminate the investment's margin. The key is to obtain the annual assessment amount and any delinquent arrears before you set your maximum bid. Factor those costs into your after-repair-value calculation the same way you would factor repair costs. A property in a CDD district is not automatically a bad deal — it depends entirely on whether your bid already accounts for the full obligation.
What is a Mello-Roos district and why does it matter at a tax deed auction?
A Mello-Roos Community Facilities District is a special tax district in California — and a few other states — that levies a special tax on parcels within the district to repay bonds issued for infrastructure improvements. The tax appears as a separate line item on the property tax bill. Because Mello-Roos districts have independent enforcement authority, a delinquent Mello-Roos levy may have generated a separate lien or foreclosure proceeding that was not part of the tax deed foreclosure you are bidding at. This means the obligation could survive your deed. Researching the Mello-Roos district's records separately from the county tax records is essential for any California parcel.
More guides
- Tax Deed vs Tax Lien: What's the Difference? (2026 Guide)
- Is Tax Deed Investing Safe? 6 Risks to Check Before You Bid
- Tax Deed Surplus Funds: How Overbid Recovery Works
- Redeemable Deed States Explained (Georgia, Texas & More)
- Probate Estates, Heir Disputes, and Ownership Gaps at Tax Deed Auctions: What Every Investor Must Evaluate Before Bidding
- Utility Easements, Rights-of-Way, and Hidden Encumbrances at Tax Deed Auctions: What Every Investor Must Know Before Bidding
Informational only, not legal or investment advice. Confirm rules with the county and consult a licensed professional before bidding.