Mixed-Use Properties at Tax Deed Auctions: Zoning Complexity, Income Disruption, and the Risks Every Investor Must Evaluate Before Bidding
Mixed-use properties—buildings that combine retail, office, or industrial space with residential units—appear regularly at tax deed auctions and often look like compelling value plays. But the same complexity that makes them attractive to tenants makes them dangerous for unprepared bidders. Before you raise your paddle, you need to understand how zoning, lease rights, code obligations, and lien priority interact in a way that no single-use property ever creates.
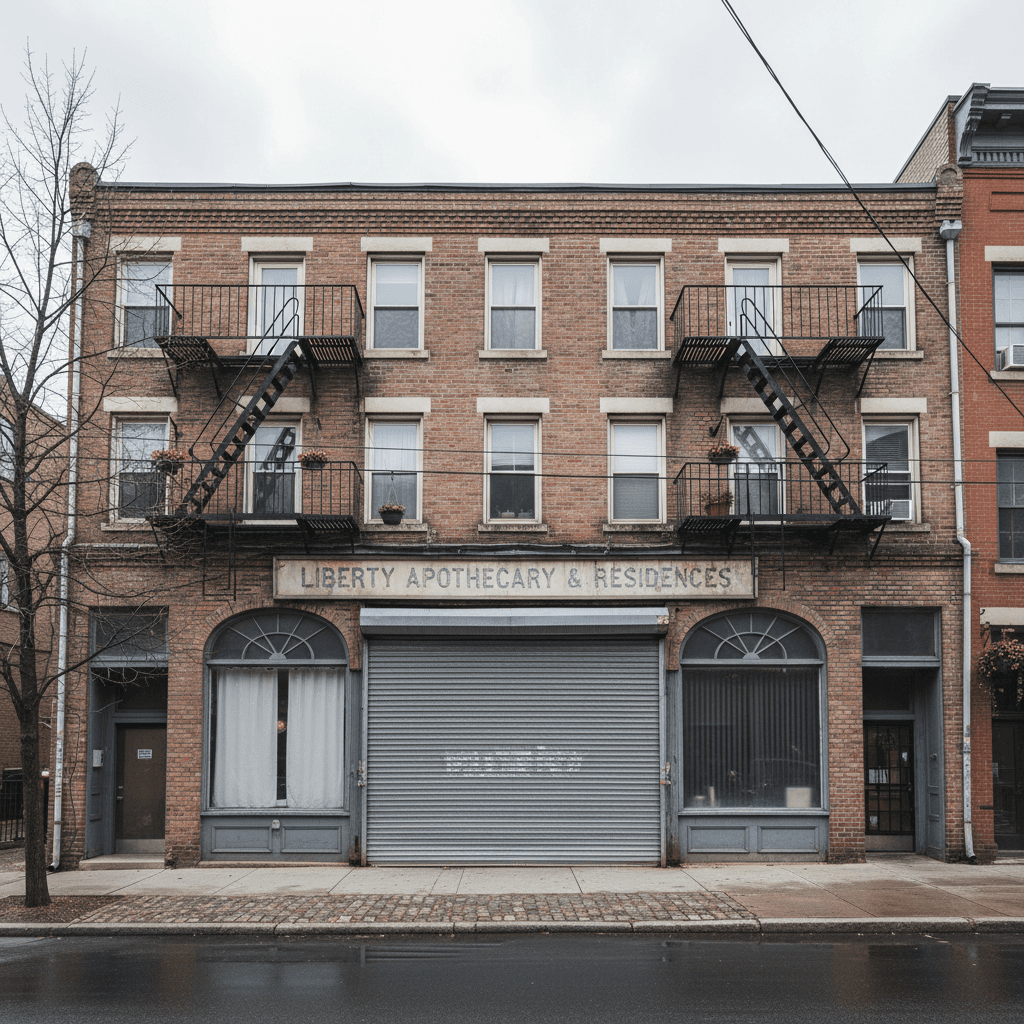
What Makes Mixed-Use Different From Any Other Tax Deed Purchase
A standard single-family tax deed purchase already demands careful due diligence on surviving liens, redemption windows, and title gaps. A mixed-use property stacks an entirely separate layer of regulatory and contractual risk on top of every one of those concerns. You are not just acquiring a building—you are potentially stepping into a landlord relationship with commercial tenants, inheriting existing certificates of occupancy issued under prior ownership, and taking on a structure that must simultaneously satisfy residential habitability codes and commercial building standards.
The county tax rolls often list a mixed-use parcel under a single APN with a blended assessed value. That simplicity on paper obscures what can be a legally fragmented asset: one portion subject to residential homestead rules, another governed by commercial zoning, and still another potentially operating under a conditional use permit or a special-exception variance granted to the prior owner personally rather than to the property itself.
- Residential portion may carry different lien priorities than the commercial portion
- Conditional use permits can expire on transfer of ownership
- A single APN does not mean uniform legal treatment across all uses
Zoning Verification: The First Non-Negotiable Step
Before estimating any value or exit strategy, confirm what the zoning ordinance actually permits on the parcel today—not what the prior owner was operating. Mixed-use designations vary enormously by municipality. Some jurisdictions maintain a formal MU or UC (urban commercial) overlay district that explicitly authorizes ground-floor retail with upper-floor residential. Others rely on spot variances, which are discretionary approvals that can be personal to the applicant and do not automatically run with the land.
If the prior owner was operating a restaurant on the ground floor under a conditional use permit tied to their liquor license or their specific business entity, that permit may not transfer to you. You could own a ground-floor commercial space that is legally constrained to uses you cannot immediately pursue without re-applying to a planning board—a process that can take months and is never guaranteed. Contact the municipal planning or zoning department directly and ask for the current zoning classification, any active variances, and whether those variances are personal or appurtenant to the land.
- Request the zoning verification letter or official zoning certificate from the municipality
- Ask specifically whether any variance, special exception, or CUP is transferable
- Check if nonconforming use status applies and whether a gap in operation could extinguish it
Surviving Commercial Leases: The Tenant Rights Problem
One of the most underestimated risks in mixed-use tax deed investing is the commercial lease that survives the sale. Under federal law and many state statutes, a tax deed sale does not automatically terminate a valid commercial tenancy in the same way a residential eviction notice might. The Protecting Tenants at Foreclosure Act primarily addresses residential tenants, but commercial leases often carry their own survival protections depending on how the lease was structured and recorded.
If a ground-floor commercial tenant signed a long-term lease—say, a five-year agreement with two five-year options—and that lease was recorded in the chain of title before the tax lien arose, the tenant may argue that the lease survives your deed. Even if it does not legally survive, evicting a commercial tenant who refuses to vacate requires a formal unlawful detainer or ejectment proceeding in civil court, not a simple owner-occupancy notice. That litigation is time-consuming and expensive. Worse, if the prior owner collected security deposits and prepaid rent that were never applied, you could face claims from the tenant for those funds you never received.
Always pull the chain of title to identify any recorded leases or memoranda of lease. Review them against the timeline of the tax lien to evaluate which leases predate the lien and which are junior. Then consult a local real estate attorney about the specific state's treatment of pre-existing commercial tenancies in a tax deed context.
- Search for recorded memoranda of lease in the county recorder's index
- Identify whether any lease predates the delinquency that triggered the tax deed
- Verify whether the state's tax deed statute expressly terminates pre-existing leases or is silent on the issue
Code Compliance and Certificate of Occupancy Gaps
Mixed-use buildings are subject to dual inspection regimes. The residential units must satisfy local housing and building codes—minimum habitability standards, electrical, plumbing, ventilation. The commercial space must satisfy commercial occupancy standards, fire suppression requirements, ADA accessibility provisions, and potentially health department regulations if food service was ever involved. When a property falls into tax delinquency, deferred maintenance is almost always part of the story. Inspections lapse. Permits get pulled but never closed. Code violations accumulate.
A critical issue specific to mixed-use is the certificate of occupancy. If the CO was issued for the combination of uses under the prior owner's build-out and the current physical condition of the building has since changed—whether through unpermitted alterations, storm damage, or simply age—you may not be able to operate any portion of the building until a new CO is obtained. In some jurisdictions, a change of ownership itself triggers a fresh inspection requirement. You could acquire a building at auction and be unable to legally rent either the commercial or residential space until you remediate code violations you had no opportunity to inspect before bidding.
Request any available code violation records from the local building department. Check for open permit history. Look for active stop-work orders. Even if interior access is impossible before the auction—as is common with occupied tax deed properties—a review of public permit records and violation notices costs nothing and reveals a great deal.
- Order a code violation search from the building department and any municipal housing office
- Check permit history for unpermitted work on both commercial and residential portions
- Ask whether a change-of-ownership inspection is required in that jurisdiction
Lien Priority and the Mixed-Use Complication
Senior liens on mixed-use properties can be surprisingly complex to untangle. A mechanic's lien filed by a contractor who renovated only the commercial storefront theoretically attaches to the entire parcel if it was filed against the full APN. A commercial mortgage taken by the prior owner against the whole property does not split neatly between residential and commercial value for priority purposes. Municipal water and sewer liens—which survive tax deed sales in many states—may reflect commercial-scale consumption from the restaurant or laundromat that operated below, not residential usage, meaning the arrears can be substantially larger than they appear at first glance.
The IRS federal tax lien, if one exists, attaches to all property owned by the taxpayer without distinguishing use type. If the prior owner operated a business on-site and generated federal payroll or income tax liabilities, a federal tax lien may be lurking in the chain of title. The IRS retains a 120-day right of redemption after a tax deed sale, during which it can step in and acquire the property by paying your purchase price plus interest. On a mixed-use building where commercial income was historically significant, the IRS redemption risk is worth taking seriously.
Run a full title search before bidding. That means not just the county property index but also the federal tax lien index maintained by the Secretary of State or county recorder, UCC filings that may reflect security interests in business fixtures attached to the commercial space, and any recorded subordination agreements or SNDA agreements (Subordination, Non-Disturbance, and Attornment) that could affect tenant rights.
- Search the federal tax lien index for IRS liens attached to the prior owner's EIN or SSN
- Identify all municipal lien types—water, sewer, trash, code violations—and confirm whether they survive the deed in that state
- Review whether any commercial equipment or fixtures were financed separately and carry UCC security interests
Evaluating Exit Strategy Before You Bid
The exit strategy you plan for a mixed-use property must be viable under current zoning and code conditions—not under the assumption that everything the prior owner was doing was legal and transferable. If you plan to continue operating both residential and commercial uses, confirm you can legally do so under your ownership without re-approval. If you plan to convert to purely residential use, confirm that the current zoning permits it and that the conversion does not trigger a loss of any residential density bonus tied to the mixed-use designation. If you plan to sell quickly, understand that your buyer's title insurer will scrutinize the tax deed chain at least as carefully as you should—and that most title insurers require a quiet title action before issuing a policy on a tax deed property regardless of property type.
The Safety Score that a platform like TaxDeedIQ generates for a given parcel aggregates multiple risk layers into a single signal—surviving lien exposure, redemption risk, flood zone designation, homestead status, and other flags—giving you a structured starting point before you commit to deep due diligence. For mixed-use parcels, that starting-point risk assessment is particularly valuable because the number of variables that can interact unfavorably is simply higher than for a single-use residential lot. Use every tool available to evaluate the risk before you bid, then verify your findings with county records and a licensed attorney familiar with your target state's tax deed statutes.
Don't buy someone else's debt
See exactly what can survive a tax deed, before your money is on the block. Every auction, scored 0–100.
Score my first auction, freeMixed-Use Properties at Tax Deed Auctions FAQ
Do commercial leases survive a tax deed sale?
It depends on the state's tax deed statute and when the lease was recorded relative to the delinquency. Some state statutes expressly extinguish all junior interests including leases; others are silent, leaving the question to litigation. If a lease was recorded before the tax lien arose, the tenant may argue the lease is senior to the deed. Always review the recorded chain of title for memoranda of lease and consult a local real estate attorney before bidding on any occupied mixed-use property.
Can I lose my right to operate the commercial portion after the tax deed auction?
Yes. Conditional use permits and variances are sometimes personal to the prior applicant and do not transfer automatically with the deed. If the commercial use was authorized by a permit tied to a specific individual or business entity, you may need to re-apply to the local planning board before legally operating that space. Verify the zoning status and transferability of any active permits directly with the municipal planning department before the auction.
Are municipal liens on a mixed-use property larger than on a residential property?
Often, yes. Water and sewer arrears on a building that housed a commercial operation—a restaurant, laundromat, or salon—can be substantially higher than typical residential utility debt. Municipal liens for code violations can also accumulate at a faster rate on commercial-facing portions of a mixed-use building. Because many municipal liens survive a tax deed sale regardless of property type, you need to research all outstanding utility and code violation balances with the municipality before placing a bid.
What is the IRS 120-day redemption risk on a mixed-use property?
If the prior owner had a federal tax lien recorded against them, the IRS has a statutory right to redeem the property within 120 days of a tax deed sale by paying your purchase price plus interest. On a mixed-use property where the prior owner also ran a business, the risk that a federal tax lien exists is elevated because business-related tax liabilities—payroll taxes, corporate income taxes—are a common source of IRS liens. Search the federal tax lien index as part of your title research before bidding.
How does TaxDeedIQ help with mixed-use property risk evaluation?
TaxDeedIQ assigns each auctioned parcel a 0-100 Safety Score that flags risk layers including surviving lien exposure, IRS redemption risk, flood zone designation, and homestead status. For mixed-use properties, this gives investors a structured risk signal to prioritize which parcels warrant deeper due diligence. The platform does not replace a full title search or legal review, but it helps you identify high-risk parcels before you spend time and money on research that could reveal a deal-breaker.
More guides
- Tax Deed vs Tax Lien: What's the Difference? (2026 Guide)
- Is Tax Deed Investing Safe? 6 Risks to Check Before You Bid
- Tax Deed Surplus Funds: How Overbid Recovery Works
- Redeemable Deed States Explained (Georgia, Texas & More)
- Short Sale vs. Tax Deed Auction: Key Differences Every Distressed-Property Investor Must Understand
- Mobile Home Parks at Tax Deed Auctions: Infrastructure Liabilities, Surviving Liens, and the Risks Every Investor Must Evaluate Before Bidding
Informational only, not legal or investment advice. Confirm rules with the county and consult a licensed professional before bidding.