Mobile Homes at Tax Deed Auctions: Title Traps, Surviving Liens, and What Investors Must Evaluate Before Bidding
A mobile home sitting on a tax-deed parcel looks like a bonus — a structure already in place at a price set by delinquent taxes. But that structure may be titled as a motor vehicle, secured by a UCC financing statement, and legally owned by someone completely different from the land's former owner. Evaluating the risk before you bid is not optional; it is the only way to avoid paying real-property auction prices for a parcel that yields nothing but land.
Why Mobile Homes Create a Dual-Title Problem at Tax Sales
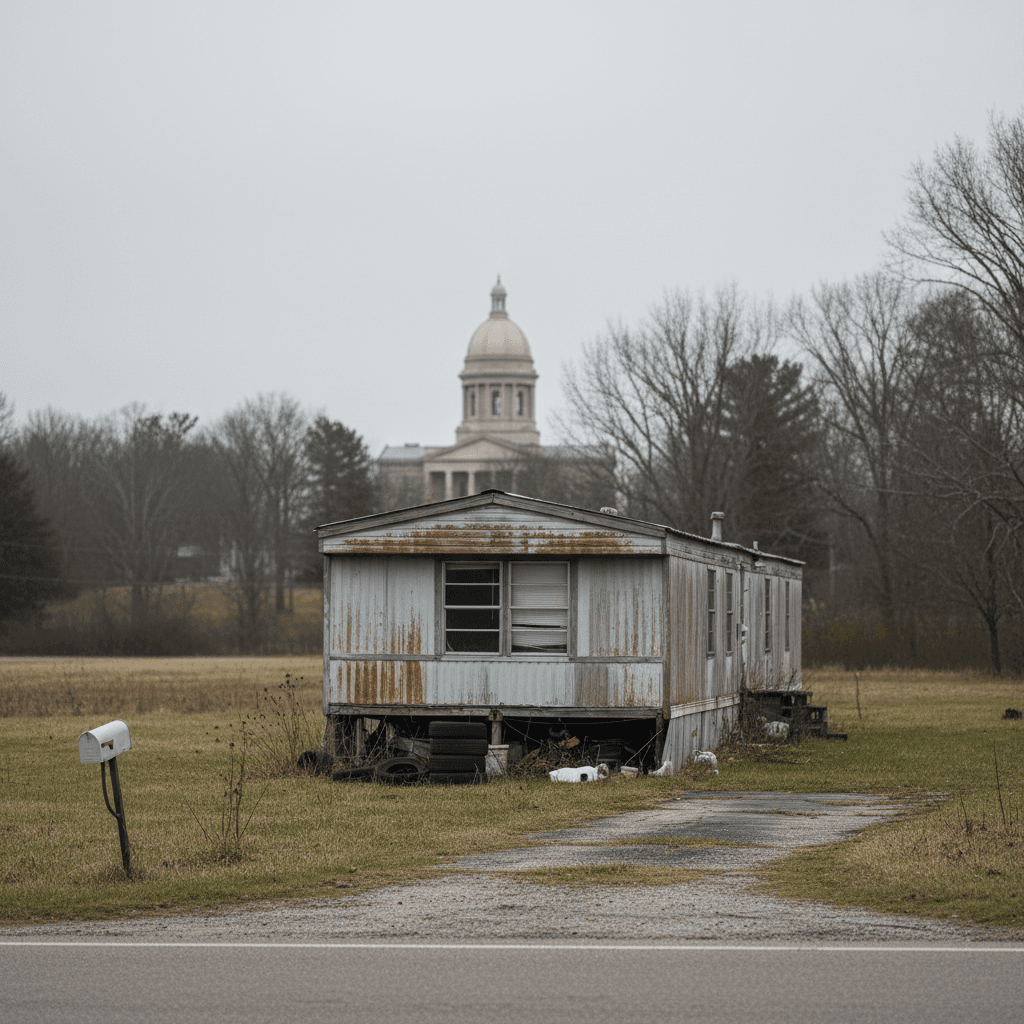
In most states, a manufactured or mobile home begins its life as personal property titled through the state's department of motor vehicles or a similar titling agency — not through the county recorder's deed records. When a county forecloses on delinquent real-property taxes and issues a tax deed, that deed conveys the land (and improvements that are legally part of the real property). If the home has never been formally converted to real property, the tax deed may transfer the land underneath the structure while leaving the home itself titled in someone else's name entirely.
The result is a legal split that surprises many first-time bidders: you win the auction, take possession of the parcel, and then discover the structure sitting on it belongs to a prior owner, a lender, or an estate — none of whom participated in the tax sale. Understanding whether a home has been 'de-titled' or 'affixed' to the real property before you bid is the single most important title question in manufactured-home investing.
- Real property deed — recorded with the county, conveys land and affixed structures
- DMV or state agency title — governs manufactured homes still classified as personal property
- UCC financing statement — can create a secured lien on a home regardless of its title classification
How States Handle the Conversion from Personal to Real Property
Most states have a statutory process — sometimes called 'affixation,' 'retirement of title,' or 'conversion' — that lets a homeowner permanently attach a manufactured home to a foundation, surrender the DMV title, and record a document in the deed records that makes the home part of the real estate. Once that process is complete, a tax deed will typically convey both the land and the home in one instrument.
The problem is that this process is voluntary and often skipped. Owners move homes onto land, hook up utilities, and live there for years without ever completing affixation paperwork. State laws differ on what triggers real-property status — some require a permanent foundation and a recorded affidavit; others look at whether wheels and axles have been removed; a few apply a facts-and-circumstances test that courts still argue about. Before you bid, verify the home's legal classification in that specific state and county, not in the state you last invested in.
Some states have passed updated manufactured-housing statutes in recent years that change the conversion requirements or retroactively alter how existing titles are treated. Check current law with a licensed real estate attorney in the relevant jurisdiction — this is an area where the rules are actively evolving.
UCC Liens on Manufactured Homes: The Financing Statement Problem
When a buyer finances a manufactured home through a lender — whether a bank, a credit union, or a dealer's financing arm — the lender often perfects its security interest by filing a UCC-1 financing statement in the state's central filing office rather than (or in addition to) recording a mortgage in the county deed records. A tax deed, which wipes out junior liens recorded against the real property, does not automatically extinguish a properly perfected UCC lien on personal property. The two lien systems operate in parallel, and a tax deed foreclosure may not even be noticed by the UCC secured party.
This means an investor who buys a parcel at tax deed auction could face a lienholder who still has a valid security interest in the home sitting on the land. That lienholder can, in theory, repossess the structure. Before bidding, search the state's UCC filing database for the property address and for the names of any prior owners you identify through the deed chain. An open financing statement with a balance is a serious red flag that demands resolution before you close, not after.
- Search the Secretary of State's UCC database by debtor name and property address
- Check whether the UCC filing has been terminated or renewed — filings lapse after a set period but can be renewed
- Ask whether the secured party received legally required notice of the tax sale; defective notice can create liability
Surviving Liens Specific to Manufactured Housing Communities
Investors who bid on a lot within a manufactured housing community or mobile home park face an additional layer of risk. Even if the home is classified as real property and the tax deed is clean, the lot may be subject to ground lease arrears, community association charges, or utility back-bills that are assessed against the home rather than recorded in traditional lien form. Some states allow manufactured housing communities to file a lien for unpaid lot rent that attaches to the home as personal property — again, invisible in deed records.
Code-enforcement violations are another recurring hazard. Older mobile homes in particular accumulate municipal violations — from HUD-code compliance issues to local housing codes — that generate enforcement liens. Depending on the jurisdiction, those liens may survive a tax deed sale just as code-enforcement liens on site-built homes can. A visual inspection of the structure and a check with the local building or housing department before bidding will often reveal outstanding orders that translate directly into required capital expenditure.
If the parcel is in a flood zone, manufactured homes face heightened FEMA elevation requirements for any substantial improvement, which can make renovation costs far exceed what you modeled based on land value alone. Verify the FEMA flood zone designation and understand the elevation certificate requirements for the structure before bidding.
- Lot-rent arrears liens filed against the home as personal property
- Municipal code-enforcement orders and notices of violation
- FEMA flood zone elevation requirements for substantial improvement
- Outstanding utility liens assessed to the structure rather than the land record
Due Diligence Checklist Before Bidding on a Mobile Home Parcel
The extra title complexity of manufactured homes does not make them uninvestable — it makes pre-bid due diligence more time-consuming and more consequential. Start with the deed records to confirm whether an affixation or retirement-of-title document was ever recorded. If not, pull the state DMV title history to identify the registered owner and any lienholder on record. Cross-reference that with the UCC database.
Next, identify whether the home is on its own deeded lot or sits on leased land; a tax deed on a ground-lease lot conveys nothing about the home's ownership and may not give you any right to the structure at all. Confirm the property tax parcel combines land and improvements or is assessed separately. Some counties assess the home on a separate personal-property tax bill — meaning the structure itself could have its own delinquent tax obligation that is not resolved by the real-property tax deed you are buying.
Run a lien search through the county recorder, check for UCC filings, contact the local code-enforcement office, and review any homeowners or community association records. Tools that aggregate public records and flag known risk categories — surviving liens, IRS redemption windows, flood zone status, and homestead exemptions — can sharpen your analysis, but they supplement rather than replace verification with the county and a licensed professional in the relevant state.
- Confirm affixation status in deed records before the auction
- Pull DMV title history for the home's registered owner and lienholders
- Search UCC database at the state Secretary of State level
- Check for a separate personal-property tax bill on the structure
- Inspect for code-enforcement violations and outstanding municipal orders
- Verify flood zone and elevation certificate requirements
- Consult a licensed real estate attorney familiar with that state's manufactured-housing law
Don't buy someone else's debt
See exactly what can survive a tax deed, before your money is on the block. Every auction, scored 0–100.
Score my first auction, freeMobile Homes at Tax Deed Auctions FAQ
Does a tax deed automatically include the mobile home on the property?
Not necessarily. If the manufactured home was never formally converted from personal property to real property through the state's affixation or de-titling process, the tax deed conveys only the land. The home remains titled separately, potentially in the name of a prior owner or a secured lender. Always verify the home's legal classification before bidding.
Can a lender repossess a mobile home after I win a tax deed auction?
If the lender holds a valid UCC security interest or a DMV-recorded lien that was not extinguished by the tax sale — because the home was never classified as real property — the lender's rights to the structure may survive. You could end up owning the land while the lender reclaims the home. Searching the UCC database and the state titling agency's records before bidding is the only way to identify this risk.
What should I do if I discover the mobile home is still titled as personal property after winning the auction?
Consult a real estate attorney licensed in that state immediately. Depending on the circumstances, you may be able to negotiate with the DMV-titleholder or pursue a quiet title action, but the outcome varies by state law and the specific facts. This is a situation where acting without legal guidance can make the title problem significantly worse.
Are lot-rent arrears a lien that survives the tax deed on a manufactured home parcel?
It depends on state law and how the lien was perfected. Some states allow manufactured housing community operators to file a lien for unpaid lot rent that attaches to the home as personal property. That lien may not appear in county deed records and may not be extinguished by a real-property tax deed. Check with the community management and search state-level personal-property lien records before bidding.
How does a flood zone designation affect a mobile home I acquire through a tax deed?
FEMA regulations impose strict elevation requirements when a manufactured home in a Special Flood Hazard Area undergoes substantial improvement or is replaced. Even if the structure is habitable today, any significant renovation work may trigger compliance requirements that add substantial cost. Verify the FEMA flood map designation and understand the applicable elevation certificate requirements before you calculate your maximum bid.
More guides
- Tax Deed vs Tax Lien: What's the Difference? (2026 Guide)
- Is Tax Deed Investing Safe? 6 Risks to Check Before You Bid
- Tax Deed Surplus Funds: How Overbid Recovery Works
- Redeemable Deed States Explained (Georgia, Texas & More)
- Property Condition Risk at Tax Deed Auctions: Inspections, Hidden Defects, and What You Can't See Before You Bid
- Partial Interest and Undivided Ownership at Tax Deed Auctions: The Hidden Risk That Can Lock Up Your Investment
Informational only, not legal or investment advice. Confirm rules with the county and consult a licensed professional before bidding.