How to Buy Tax Deeds in Georgia: Courthouse Steps Sales, Redeemable Deeds, and the Risks Investors Must Evaluate First
Georgia conducts tax deed sales on courthouse steps every month, making it one of the most active and accessible states for deed investors. But Georgia's 'redeemable deed' structure means you do not own the property outright the moment the gavel falls — the former owner can take it back. Understanding exactly how that works, what survives the deed, and what due diligence you must complete before the first Tuesday of the month could be the difference between a profitable investment and an expensive lesson.
- State
- GA
- Sale
- Redeemable
- Redemption
- 12 mo
- Rate
- 20%
The former owner has 12 months to redeem. Until then you do not hold clear possession.
See all 50 state rules →How Georgia's Tax Sale Process Works
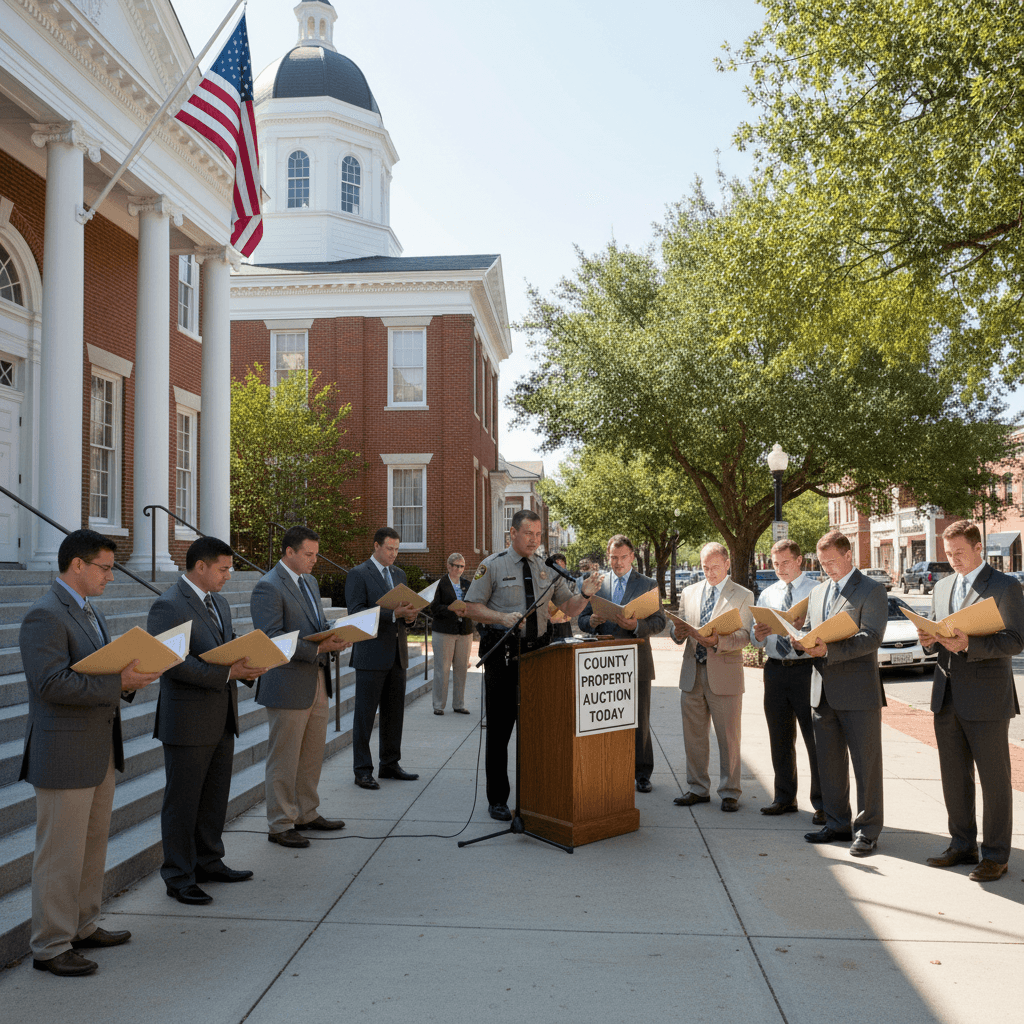
Georgia tax sales are administered at the county level by the county tax commissioner or tax collector. When a property owner falls delinquent on ad valorem property taxes, the county follows a statutory notice and levy procedure that ultimately results in the property being advertised and sold at a public auction. By law, these sales are held on the first Tuesday of the month at the county courthouse, which is why Georgia investors commonly call them 'courthouse steps' sales.
The winning bidder receives a 'tax deed to realty' — a document that conveys the county's interest in the property. However, this is not a warranty deed and it is not a clean title instrument. The deed conveys what the taxing authority had the legal right to sell, which may include title defects, encumbrances, and a statutory right of redemption that keeps the former owner in the picture for a defined period after the sale.
Each county publishes a list of properties scheduled for sale, typically in the official county legal organ — a designated local newspaper — for four consecutive weeks before the auction. Investors who want early access to these lists should contact the county tax commissioner's office directly or monitor the legal organ for upcoming sales.
- Sales held: First Tuesday of each month
- Administering authority: County tax commissioner or tax collector
- Notice requirement: Four weeks in the official county legal organ
- Deed type: Tax deed to realty (not a warranty deed)
Georgia's Redeemable Deed: The Right of Redemption You Must Price In
Georgia's tax deed is a redeemable deed, which means the property's former owner — and in some circumstances, other parties with a legal interest — retains the right to reclaim the property after the sale by paying a redemption amount. Georgia law sets this redemption window at twelve months from the date of the sale for most properties. Certain property types, including owner-occupied residential properties, may carry extended protections or specific procedural requirements that the investor should verify with the county and a Georgia-licensed attorney before bidding.
To redeem the property, the former owner must pay the high bid amount plus a statutory premium on top of that figure. That premium is set by statute and is intended to compensate the investor for the risk taken. If redemption occurs, the investor recovers their principal plus that statutory return — but receives no appreciation, no rent, and no other benefit beyond what the statute allows. Because the return on a redeemed property is fixed, investors must calculate whether the statutory yield justifies the capital committed for up to a year.
Critically, the twelve-month redemption clock does not begin to run automatically. The deed holder must serve the former owner and all parties with a legal interest — such as mortgage lenders and junior lienholders — with a statutory notice of the right to redeem. Until proper notice is served, the redemption period may not have started, and your ability to proceed to a quiet title action or obtain marketable title can be delayed. This notice step is not optional; skipping or botching it extends the uncertainty period indefinitely.
- Redemption window: Twelve months from sale date (verify for specific property types)
- Redemption cost to former owner: High bid plus statutory premium
- Notice obligation on deed holder: Must notify owner and all interested parties to start the clock
- Consequence of missed notice: Redemption clock may not run; title remains clouded
What Liens and Encumbrances Survive a Georgia Tax Deed
One of the most consequential questions in any tax deed state is which encumbrances are extinguished by the sale and which ones follow the property to the new owner. In Georgia, the tax deed generally cuts off junior liens — including most mortgages and junior judgment liens — when the sale is properly conducted and statutory notice requirements are met. However, 'generally' is doing a lot of work in that sentence, and investors should never assume a lien is gone without verifying it in the county records and confirming with a title professional.
Federal tax liens held by the IRS occupy a special position under federal law. The IRS retains a 120-day right of redemption after a tax sale, regardless of state law. During that window, the IRS can purchase the property at the price you paid plus interest. This is not theoretical — it is a federal statute, and every investor who buys at a tax sale should check the IRS lien index for the subject property before bidding.
Special assessments for municipal improvements — road paving, sewer connections, sidewalk repairs — may survive the tax deed depending on how the assessment was created and whether it is treated as a lien running with the land. Code enforcement liens and nuisance abatement liens issued by municipalities can also survive in some jurisdictions. Environmental contamination orders issued under federal Superfund authority are generally not extinguished by a state tax sale. The cost of investigating and remediating a contaminated property can far exceed its market value, making environmental screening a mandatory step before bidding on industrial, commercial, or older residential properties.
- Federal IRS tax liens: 120-day redemption right survives the sale
- Junior mortgages and judgment liens: Generally extinguished if notice is proper
- Special assessments: May survive — verify with the municipality
- Code enforcement and nuisance liens: Survival depends on local ordinance
- Environmental/Superfund liens: Not extinguished by state tax sale
Getting to Marketable Title After a Georgia Tax Deed
Winning the bid is only the first step. A raw tax deed to realty is not insurable title — a title company will not issue a standard owner's policy on a bare tax deed, and a future buyer or lender will not accept it. To convert a Georgia tax deed into marketable title, investors typically pursue one of two paths: wait for the redemption period to expire and then file a quiet title action, or attempt to negotiate a quitclaim deed from the former owner to shorten the process.
A Georgia quiet title action is a court proceeding that names all potential adverse claimants, notifies them through publication and service of process, and asks the court to confirm that the tax deed holder has superior title. The action involves attorney fees, court costs, and a waiting period for responses. The timeline and cost vary by county and court docket. Budget for this expense before you bid — it is not an optional cost if you want to sell or refinance the property.
Some investors accelerate the process by approaching the former owner immediately after the sale and offering a modest cash payment in exchange for a quitclaim deed. When the former owner has no realistic ability to redeem — they owe more than the property is worth or simply cannot raise the funds — this negotiation can shorten the path to clear title significantly. However, this strategy carries its own risks: the quitclaim deed from the former owner does not resolve claims held by mortgage lenders or other lienholders, who received their own statutory notice rights. A title attorney must review the full chain of encumbrances before you assume the quitclaim approach solves the problem.
- Standard path: Serve notice, wait for redemption window to close, file quiet title action
- Accelerated path: Negotiate quitclaim deed from former owner (does not release lienholder claims)
- Title insurance: Not available on raw tax deed; requires quiet title or equivalent clearance
- Cost to budget: Attorney fees, court costs, publication costs for quiet title
Due Diligence Checklist Before Bidding at a Georgia Tax Sale
Because Georgia's courthouse steps sales move quickly and competitive bidding can drive prices up, the investor who wins at a reasonable margin is the one who completed due diligence before the auction, not after. The following framework reflects the categories of risk that must be evaluated on every Georgia tax deed property.
Start with the property's physical condition. Georgia tax sales frequently include properties that have been vacant, neglected, or vandalized. A drive-by inspection before the sale date is the minimum; access to the interior may not be available, but exterior condition and neighborhood context tell you a great deal about rehabilitation cost. Cross-reference the parcel with FEMA flood zone maps — properties in high-risk flood zones carry mandatory flood insurance requirements that increase carrying costs and reduce the buyer pool when you go to sell.
Next, pull a full title search from the county deed records and the superior court lien index. Identify every recorded mortgage, judgment lien, special assessment, and federal tax lien. Call the county tax commissioner to confirm the exact amount owed, including penalties, interest, and fees, so you understand what debt triggered the sale. Run the address through the EPA's environmental database to screen for Superfund designations or brownfield status. Finally, model your maximum bid using a conservative after-repair value estimate, subtract the quiet title and rehabilitation costs, subtract a risk buffer for the redemption uncertainty, and never exceed that number at auction regardless of competitive pressure.
- Physical inspection: Drive-by at minimum; note exterior condition and access issues
- Flood zone check: FEMA map for mandatory insurance exposure
- Title search: Deeds, mortgages, judgments, federal tax liens in county and superior court records
- IRS lien index: Check for federal tax liens triggering 120-day redemption
- Special assessments: Contact municipality for outstanding improvement assessments
- Environmental screening: EPA database for Superfund, brownfield, underground storage tanks
- Maximum bid calculation: ARV minus rehab minus quiet title cost minus redemption risk buffer
- Confirm sale details: County tax commissioner for exact delinquency amount and auction procedures
Score every auction before you bid
TaxDeedIQ gives every US tax deed & tax lien auction a 0–100 safety score, surviving liens, IRS redemption, flood, homestead.
Start my free trialHow to Buy Tax Deeds in Georgia FAQ
What is a redeemable deed in Georgia and how long does the owner have to redeem?
A Georgia redeemable deed transfers the county's tax sale interest to the winning bidder, but the former owner retains a statutory right to reclaim the property by paying the high bid plus a statutory premium. The redemption window is generally twelve months from the sale date, but the clock does not start running until the deed holder properly serves notice on the former owner and all parties with a recorded legal interest. Investors should verify the specific redemption terms for the property type with a Georgia-licensed real estate attorney before bidding.
Do mortgages survive a Georgia tax deed sale?
Generally, a properly conducted Georgia tax sale extinguishes junior mortgages and most other recorded liens when the statutory notice requirements are satisfied. However, the IRS retains a 120-day right of redemption under federal law regardless of state procedure, and certain other liens — including federal environmental liens and some special assessments — may survive. Because a missed or defective notice to a lienholder can revive that lienholder's claim, a full title search and review by a title professional are essential before you bid.
How do I get insurable title after buying at a Georgia tax sale?
A raw Georgia tax deed is not insurable as-is. Most investors must file a quiet title action in the superior court of the county where the property is located after the redemption period has expired. The action names all potential adverse claimants, provides court-supervised notice, and results in a judgment confirming the deed holder's title. Only after that judgment — or in some cases after clearing the title through other court-approved means — will a title company issue an owner's policy. Budget attorney fees, court costs, and publication costs into your pre-bid financial model.
Can I access the property before the Georgia tax sale auction?
There is no statutory right of entry for prospective bidders before a Georgia courthouse steps sale. Most properties sold at tax sale are occupied by the former owner or tenants, or they are vacant and may be secured. Investors are limited to drive-by inspections of the exterior. This is a significant risk factor — you are bidding on a property you cannot fully inspect. Adjust your maximum bid downward to account for unknown interior conditions, and treat any visible deferred maintenance as a floor estimate for rehabilitation cost, not a ceiling.
What happens to excess funds after a Georgia tax sale?
When the high bid at a Georgia tax sale exceeds the total amount of taxes, penalties, interest, and fees owed, the surplus is held by the county. The former owner and other parties with a legal interest — such as junior lienholders — may file a claim for those excess proceeds. Georgia law provides a process for distributing surplus funds, and claims are generally subject to a deadline. Former owners who receive notice of surplus funds and fail to claim them within the statutory window may lose access to those funds. Investors operating a surplus funds recovery practice should review the specific county's procedures and applicable state statutes carefully.
More guides
- Tax Deed vs Tax Lien: What's the Difference? (2026 Guide)
- Is Tax Deed Investing Safe? 6 Risks to Check Before You Bid
- Tax Deed Surplus Funds: How Overbid Recovery Works
- Redeemable Deed States Explained (Georgia, Texas & More)
- How to Buy Tax Deeds in West Virginia: Sheriff Sales, Redemption Rights, and the Risks Investors Must Evaluate First
- How to Buy Tax Deeds in Oklahoma: County Resale Auctions, Surviving Liens, and the Risks Investors Must Evaluate First
Informational only, not legal or investment advice. Confirm rules with the county and consult a licensed professional before bidding.